
THANK YOU FOR SUBSCRIBING

Hrtech Outlook Weekly Brief
Be first to read the latest tech news, Industry Leader's Insights, and CIO interviews of medium and large enterprises exclusively from Hrtech Outlook

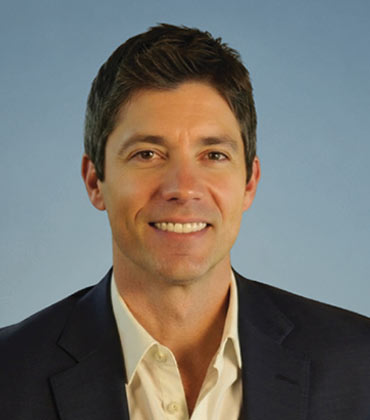 Chip Nash, Co-founder and CEO
Direct-to-employer was still an emerging channel, taking shape alongside manufacturers’ move toward direct-to-consumer models. Crux, recently named Specialty Employee Benefits Platform of the Year 2026 by HR Tech Outlook, saw an opportunity to carry that direct-channel approach into employer-sponsored benefits, establishing a route between manufacturers and the organizations funding care.
GLP-1s had set events in motion that created a rare opportunity for alignment. Member demand was accelerating, employers were facing rising costs and opaque pricing and manufacturers were increasingly open to alternative distribution channels.
“GLP-1s are really where pain and lack of transparency, member demand and manufacturer willingness all converged first,” says Chip Nash, co-founder and CEO.
Crux’s idea was straightforward. Extend manufacturer pricing beyond traditional pharmacy benefit manager (PBM) pathways, directly to employers, by building the infrastructure to handle pricing, eligibility and payment automatically. Employers could choose how much they contributed per prescription, with every dollar of that contribution flowing directly to members as a reduction in their cost.
What emerged from the initial idea now operates as a specialty-medication coverage operating adjacent to an employer’s existing health plan. Crux functions as the transaction and compliance layer behind the direct-to-employer model, turning manufacturer pricing and employer contribution decisions into a benefit that can be administered across an eligible population. It passes pricing through without a spread and can integrate optional clinical support around treatment. Manufacturers set the product and price. Employers access those terms uniformly, with transparency and choice built in as the default.
“We need to be doing a lot more to help employers because they’re really the backbone, the financial engine behind the private American healthcare system,” says Nash.
Changing What Employers Pay and How They Budget
The platform’s biggest advantage is how it exposes true prescription costs and eliminates rebate float. In a traditional PBM model, a plan may pay roughly $1,200 at the point of sale and receive a portion back months later through rebates. The amount and timing vary by contract. A mid-sized employer with roughly 1,000 covered lives and a few hundred GLP-1 users can carry close to $1 million in rebate float at any moment.
“It’s almost like an interest-free loan that they’re giving to the PBM,” says Blake Watts, head of GTM and channel partnerships.
Crux removes that rebate float from the transaction. Employers set a fixed contribution per prescription, established in advance and applied when an employee places their medication order. The net employer cost of a GLP-1 under traditional models often ranges from $600 to $700 per unit. Through Crux, employers can choose a contribution amount that fits their budget. Many land in the $200 to $300 range, reducing the employer-funded amount per prescription by half or more while preserving member access.
Knowing the contribution upfront gives employers a clearer way to budget for the benefit. In addition to setting contribution levels, employers define eligibility and estimate utilization. Crux administers those contributions through HRAs while supporting eligibility and compliance requirements. Employers work from known unit economics instead of forecasting around unpredictable rebate cycles.
“It’s really an easy math equation in terms of deciding the level of contribution per transaction and then determining an estimate on utilization,” says Shelly Scallon, head of client success. “That helps employers really budget for the year.”
Crux’s structure gives employers flexibility to align contributions with workforce needs and budget constraints, without defaulting to restrictive utilization controls.
“The solution that’s been proposed to employers to help address high costs has been these utilization controls,” says Nash. “They’re essentially barriers that are designed to make it harder for people to access the medicine.”
Making Transparency Part of the Member Experience
What employers gain in cost visibility, members gain in a clearer purchasing experience. Once an employer sets contribution and eligibility, Crux manages setup and launch communications. Members register on MyCrux, a co-branded member portal, ask their doctor or prescriber to send in the prescription and complete the purchase.
“It is a very easy consumer experience,” says Scallon. Members see the manufacturer price, platform fees, employer contribution and their remaining cost, including support for FSA and HSA payments. Transparency is part of the transaction itself, not something employers reconcile months later.
Crux sits alongside an employer’s existing health plan, creating a dedicated layer where specialty-medication pricing, eligibility and contributions can be managed. Employers determine who receives the benefit, how much they contribute and when it becomes available; Crux administers those decisions across the eligible population.
Connecting Access to Better Outcomes
Medication cost is only one barrier to treatment success. Members often discontinue therapy because of side effects, titration challenges, or insufficient nutrition and lifestyle support.
“Adherence is one of the biggest predictors of great health outcomes,” says Watts.
Crux addresses this issue by enabling critical support that extends beyond medication access. Its platform allows employers to integrate prescribing services, lifestyle programs and medical nutrition therapy into the same experience, either through existing partners or clinical partners within Crux’s ecosystem.
Crux keeps these components connected while allowing employers to choose the level of clinical support their population needs. It does not require every organization to adopt one clinical model.
Building the Model Beyond GLP-1s
GLP-1s provided the first proving ground, but Crux is building for a much broader landscape.
“We’re seeing advancements in science and medicine that will continue to hit the market into the 2030s and the 2040s,” says Nash.
New therapies in neuroscience, autoimmune disease, dermatology and other categories will bring their own challenges around affordability and access. Crux is extending its direct-to-employer infrastructure into these specialty areas, carrying forward the transparent pricing, employer-controlled contributions and compliance support established with GLP-1s.
The longer-term opportunity goes beyond pharmacy. Fertility, mental and behavioral health, musculoskeletal care and other employer-funded programs all require organizations to decide what to offer, how much to fund and which solutions best fit their workforce.
Crux’s roadmap includes comparative analytics, benefit-design support and simplified procurement to help employers make decisions across a wider benefits portfolio. Rather than treating each new program as a separate purchasing and administration challenge, Crux sees its infrastructure becoming a common layer through which employers can compare options, configure benefits and manage spending around their own priorities.
“We really haven’t even scratched the surface in terms of what our ultimate vision is,” says Nash.
That broader ambition builds on a model already gaining recognition in the market. Crux was named Specialty Employee Benefits Platform of the Year 2026 by HR Tech Outlook, reflecting its approach to giving employers greater visibility into cost, more control over contributions and a clearer path to specialty-medication access.
As Crux expands into new therapies and benefit categories, that same foundation positions the platform to help employers make increasingly complex funding decisions with greater clarity and control.
What Do Specialty Employee Benefits Platforms Help Employers Manage?
Pricing, eligibility, contributions and member access can become difficult to coordinate when benefits involve specialty medications. Specialty Employee Benefits Platforms bring those pieces into one benefit structure, giving employers a clearer way to set funding and giving members more visibility into what they pay. The focus is not simply administration. It is making a complex benefit easier to understand and budget. That distinction matters when an employer needs to balance a defined contribution with a member experience that remains easy to follow at the point of purchase.
How Does CRUX Apply the Specialty Employee Benefits Platforms Model?
CRUX uses a direct-to-employer approach centered on specialty medications. Its platform connects employers with pharmaceutical manufacturers and benefit partners while serving as a transaction and compliance layer alongside an existing health plan. Employers can set a fixed contribution per prescription, define eligibility and administer contributions through health reimbursement arrangements. Manufacturer pricing passes through without a spread, and optional clinical services can be added.
What Should Employers Look For In Specialty Benefits Platforms?
Clear pricing and predictable contribution rules matter when employers compare these platforms. A useful platform should make eligibility straightforward and show how employer funding affects the member’s share. Administrative details also deserve attention, including eligibility loading, launch support and payment options. Where treatment support is part of the benefit, employers can also consider how prescribing, lifestyle programs or medical nutrition services fit into the arrangement. The right mix depends on what the benefit is designed to cover and how much control employers want over contributions.
How Can Specialty Employee Benefits Platforms Make Medication Costs Easier To See?
A member should be able to tell what the medication costs, what the employer contributes and what remains to be paid. That visibility can reduce confusion at checkout and make the benefit easier to use without changing the underlying plan. Specialty Employee Benefits Platforms can support that visibility by presenting those amounts within the purchase process. CRUX’s MyCrux member portal shows manufacturer pricing, platform fees, employer contribution and remaining cost, while supporting FSA and HSA payments. Its transaction structure also removes rebate float, giving employers a clearer view of the benefit’s spending.
What Member Experience Does CRUX Provide Through Specialty Employee Benefits Platforms?
Members using CRUX register through a co-branded MyCrux portal, then have prescriptions submitted by their doctor or prescriber before completing the purchase. The Specialty Employee Benefits Platforms model is built around showing the employer contribution and remaining member cost clearly. Employers can also choose added support that connects members with prescribing services, lifestyle programs and medical nutrition therapy.
Where Can Specialty Employee Benefits Platforms Expand Beyond GLP-1 Medications?
CRUX began with GLP-1 medications and is extending its direct-to-employer infrastructure toward neuroscience, autoimmune disease and dermatology. That expansion shows how Specialty Employee Benefits Platforms can support additional specialty benefit areas without changing the basic need for configurable contributions, transparent pricing and compliance support.
Company
CRUX
Management
Chip Nash, Co-founder and CEO
Description
Crux is a direct-to-employer specialty benefits platform connecting employers with pharmaceutical manufacturers and benefit partners. Its model brings greater transparency, flexibility and employer choice to specialty medications while supporting benefit administration, compliance and access.